
Difference Between a $500 and $1000 Car Insurance Deductible
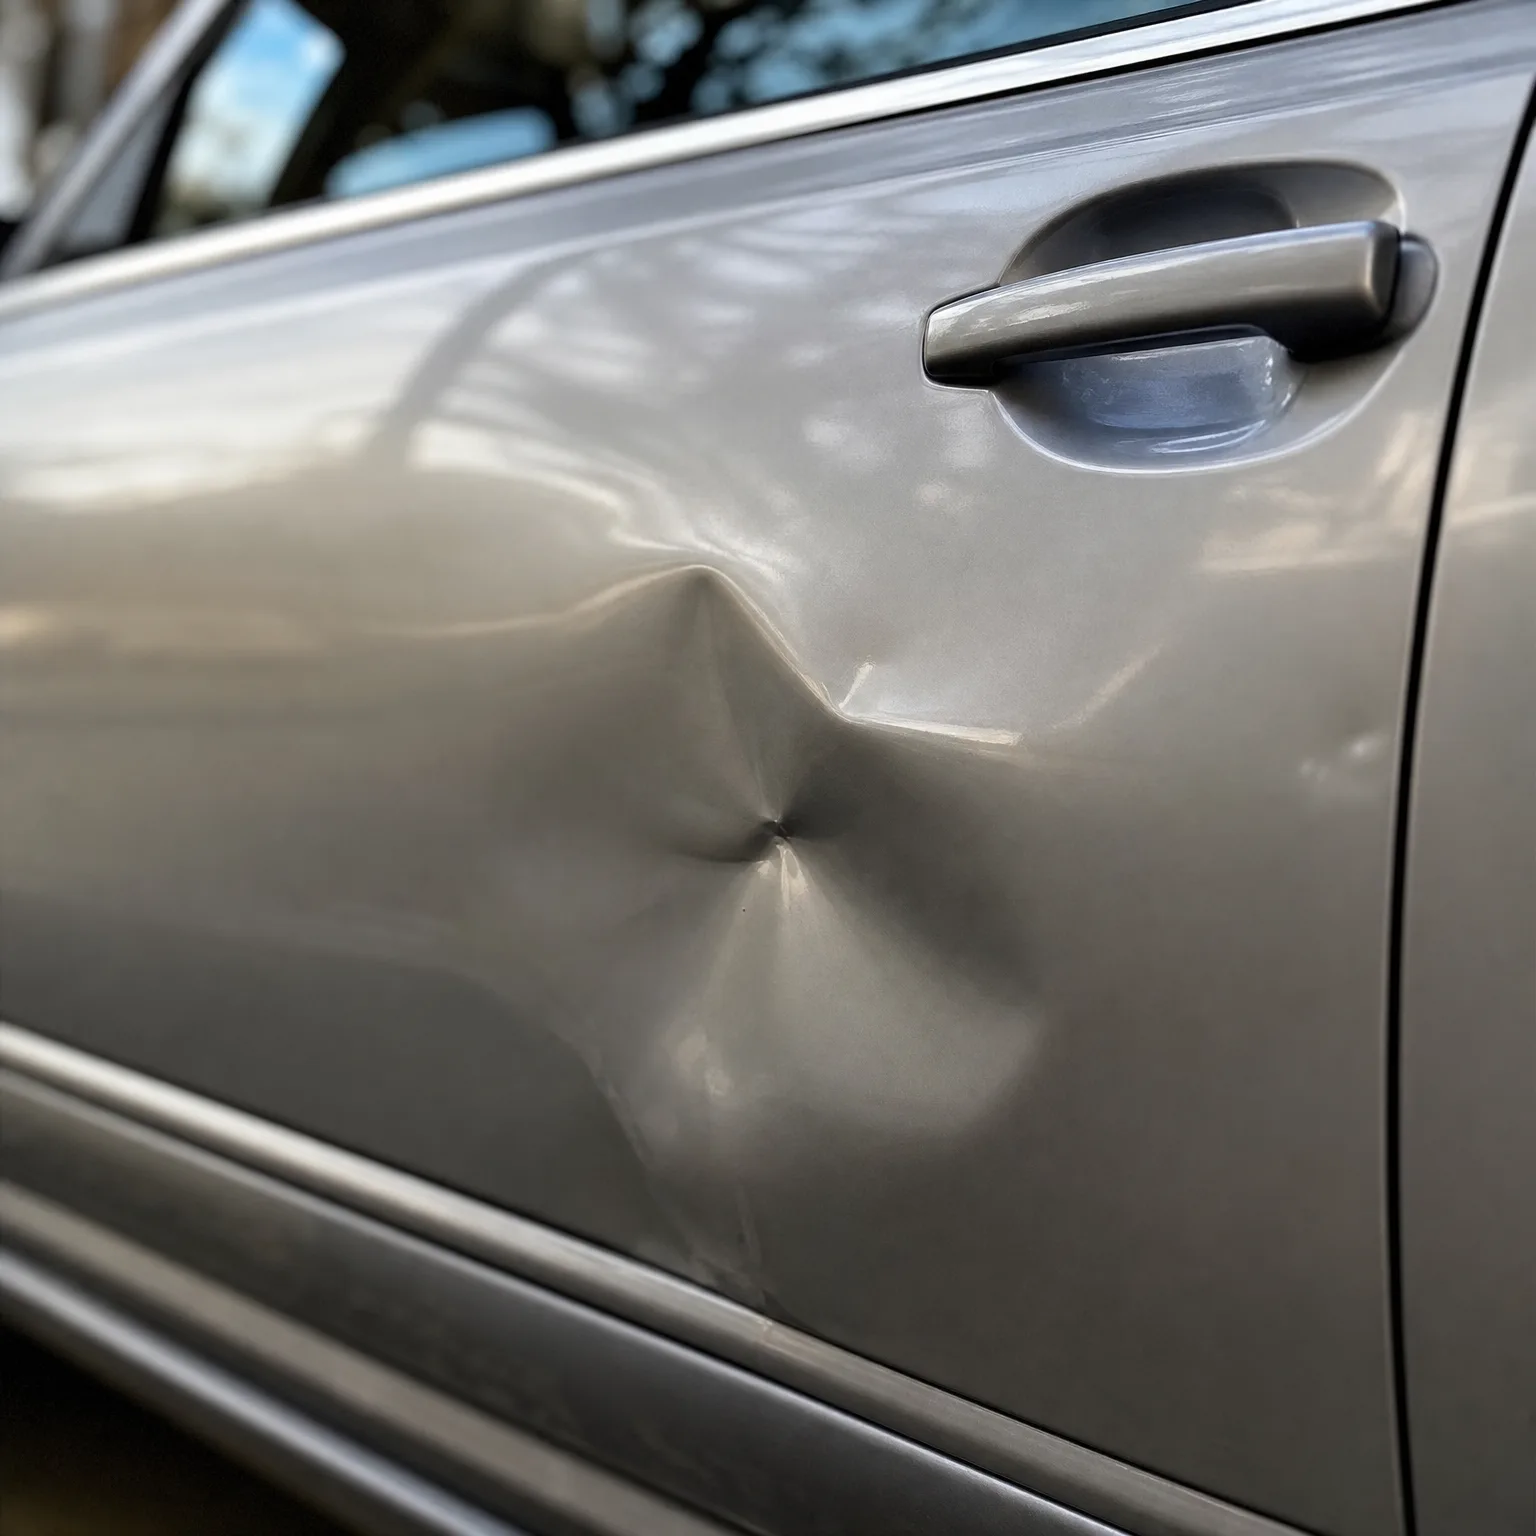
When the extra car got backed into at the grocery store
One of your kids left their old car with you when they moved out, and you kept it on your policy as a second vehicle since it still gets driven occasionally. Someone backed into it in a parking lot, and the damage came to just under a thousand dollars. You'd have paid the full repair out of pocket and kept your claims history clean. Looking back, you realized the lower deductible made sense on your main car, the one that gets driven every day, but the rarely used second car was a better candidate for the higher deductible since any damage to it is less likely and the premium savings add up over years of light use.
Should both cars have the same deductible or different ones?
They don't have to match, and for your situation they often shouldn't. The right deductible depends on how a car is used and how much cash you'd want to spend on it if something happened, not on keeping your policy simple.
A car driven daily by you benefits from a lower deductible, since it's more exposed to everyday risk and you'd want a claim to be worth filing. A car that mostly sits, or gets driven occasionally by a visiting adult child, can usually carry a higher deductible without much added risk. Splitting deductibles this way often saves money on the policy as a whole, since you're paying for lower risk on the car that needs it and higher risk tolerance on the one that doesn't.
Match the deductible to how often each car is driven, not to a single setting for the whole policy.
Now that you know which deductible fits each car, compare quotes to see what that choice actually saves you.
If you do
Your premium drops, often noticeably across two or more cars. This usually makes sense for a car driven rarely, like one kept for a visiting adult child, where the odds of a claim are already low.
If you don't
But if something happens, a fender bender, a cracked windshield, hail damage, you're out less cash immediately. This tends to fit the car you or your spouse drives daily, where claims are more likely over time.
Does my deductible change based on who drives the car, like a visiting child?
No, the deductible doesn't change based on who's driving, as long as they're a permitted driver under your policy. What matters is whether the car itself is insured and whether the visiting driver is allowed to use it, which your policy or insurer can confirm. The deductible applies to the vehicle and the claim, not to the specific driver at the time. If your child visits often enough that they're driving regularly rather than occasionally, check with your insurer about whether they need to be listed, since that's a separate question from deductible amount.
Should I raise my deductible if I'm removing my kid from the policy?
Not necessarily, and the two decisions are separate. Removing a driver who no longer lives with you or drives your cars regularly lowers your premium on its own, often by a meaningful amount, because the insurer is pricing fewer drivers and less risk. Raising the deductible is a second, independent lever you can pull for additional savings. Consider them one at a time. First confirm your child qualifies to be removed, based on where they live and whether they still drive your vehicles, then separately decide if a higher deductible fits each remaining car.
Can I have different deductibles for collision and comprehensive coverage?
Yes, in most cases insurers let you set separate deductibles for collision and comprehensive, and many households do. Comprehensive covers things like theft, vandalism, and weather damage, while collision covers crashes. Since the risks and typical claim amounts differ, it's reasonable to set a lower deductible for one and a higher one for the other. Check your policy or ask your insurer how it's currently split, since it may already be set up this way without you realizing it, and whether changing one affects the other.



