
What Is a Good Deductible for Car Insurance
A good deductible is the highest amount you could pay today without trouble, no more and no less.
The right deductible matches your savings, not your habits
A deductible is the amount you pay before your insurer pays the rest of a claim. Raising it lowers your premium because you're telling the insurer you'll absorb more of the small stuff yourself. Lowering it raises your premium because the insurer is taking on more of the risk. Neither number is correct in general. What matters is what you can actually cover the day something happens.
For a household like yours, with fewer drivers and cars than a few years ago, this is worth revisiting. A deductible that made sense when a teenager was learning to drive, where a lower number felt safer against a likely fender bender, may not fit now that the risk profile of your household has changed. With fewer miles driven and more experienced drivers on the policy, claims become less frequent, which is often the moment to consider a higher deductible in exchange for a lower bill.
The tradeoff only works if the premium savings are real and if you have the cash set aside to cover the higher amount. If raising your deductible only shaves a small amount off your bill, it's not worth the added risk. If it meaningfully lowers your premium and you have the money sitting in savings anyway, it usually makes sense.
This also depends on the car. An older car with low value might not need comprehensive or collision coverage at all, which makes the deductible question irrelevant for that vehicle. A newer or financed car still needs that coverage, and that's where the deductible choice matters most.
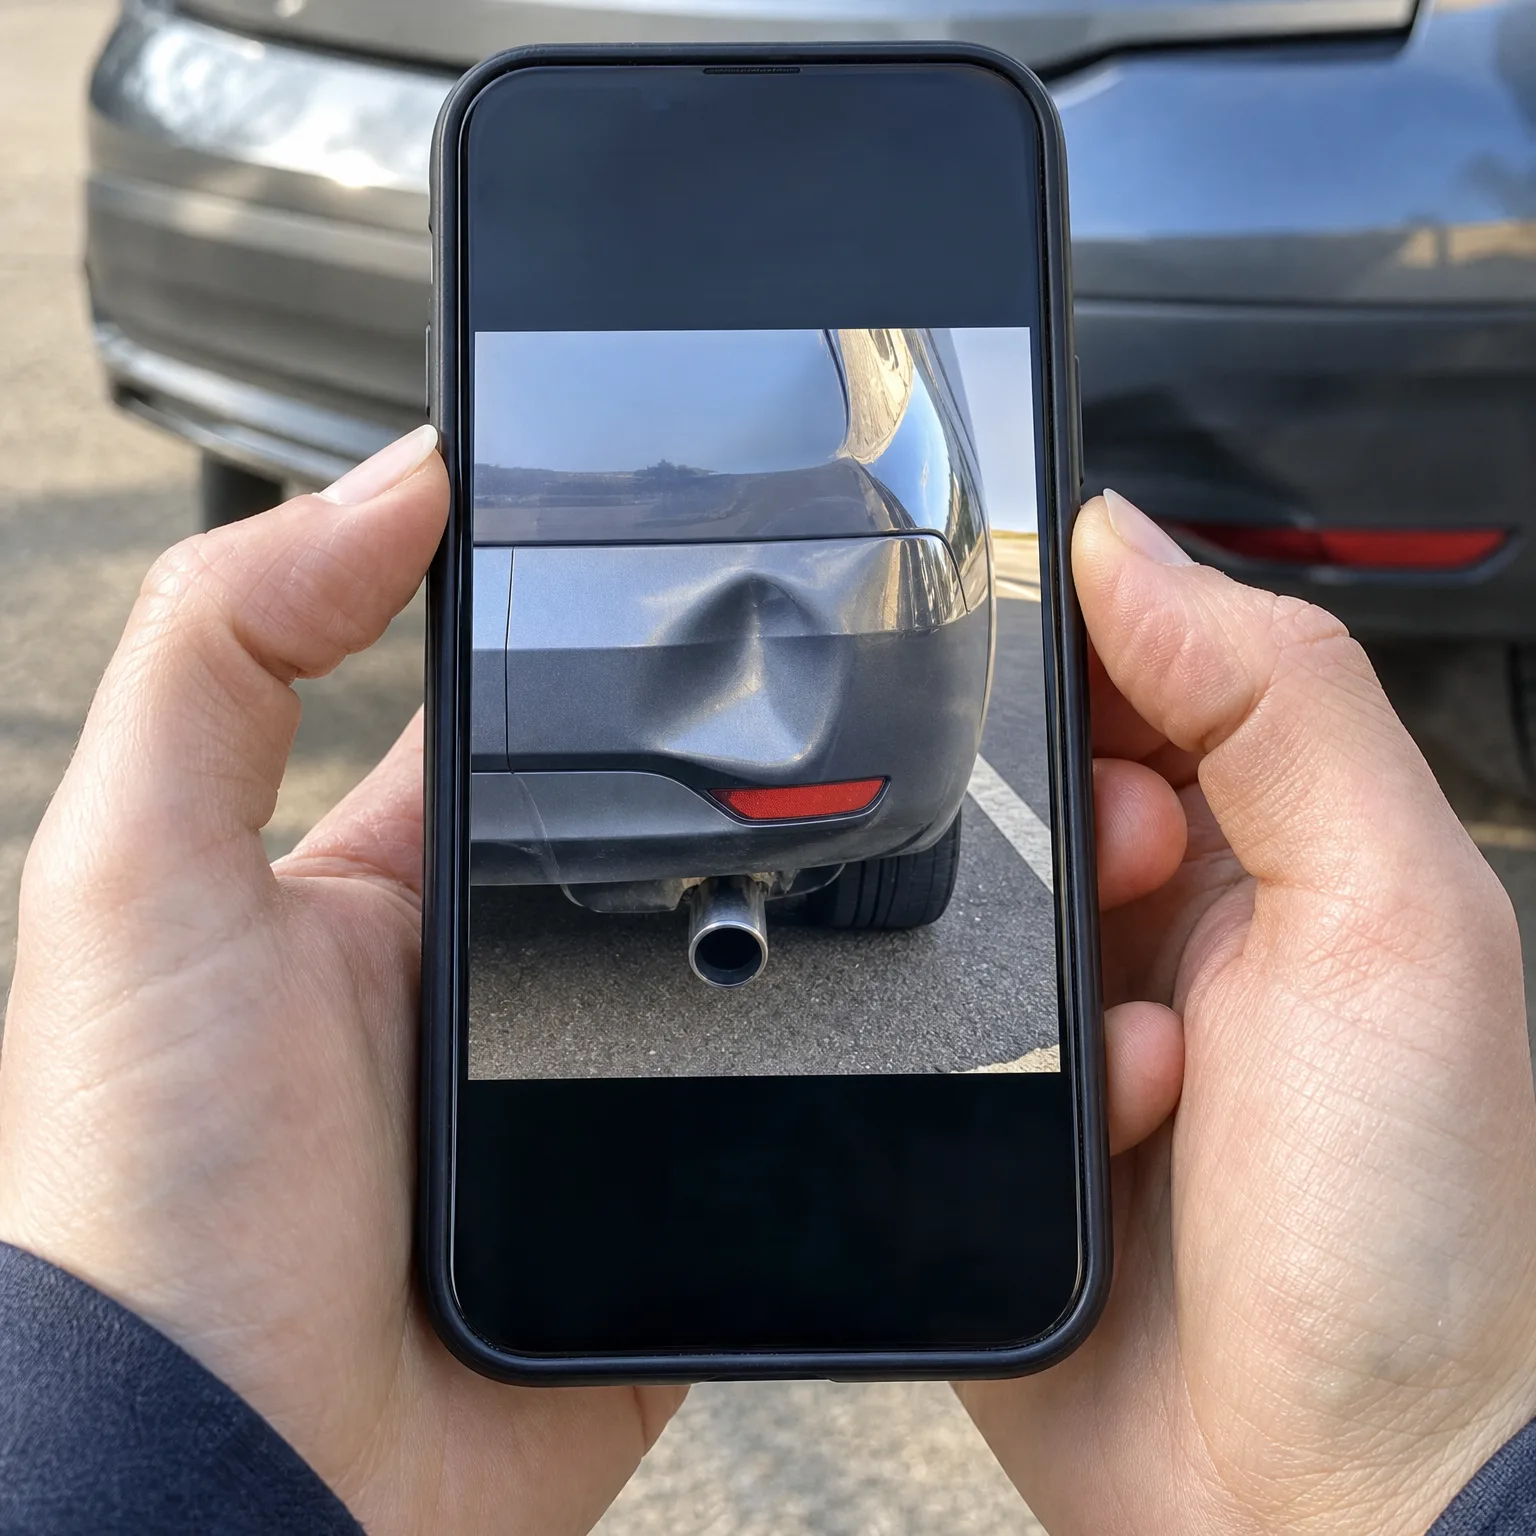
How to pick the right number for your situation
- Check your savings first Pick a deductible you could pay in cash without disrupting your budget. If covering it would mean dipping into money set aside for something else, it's too high.
- Compare the actual savings Ask for quotes at a few deductible levels side by side. If the difference is small, staying lower is simpler and safer.
- Separate by vehicle An older, low-value car may not need collision coverage at all. Review each car on your policy on its own terms, not as a single bundle.
- Factor in who drives each car A car driven occasionally by a visiting adult child carries different risk than one driven daily. Let usage guide the deductible, not just the car's value.
- Revisit it yearly Your situation has changed since the policy was set up. Review the deductible whenever your household, cars, or drivers change again.
Should you pick a different deductible for each car?
Yes, and most insurers let you do this. Each vehicle on your policy can carry its own deductible, so a car driven daily by an experienced adult can have a higher deductible than one used occasionally or by a less experienced driver. This isn't an exception, it's how the coverage is designed to work.
Think about how each car is actually used now. A car that mostly sits in the driveway and gets driven only when your adult child visits carries less risk than the car used for a daily commute. Setting the quieter car's deductible higher, if the savings justify it, while keeping the frequently driven car's deductible lower can balance savings against peace of mind. Ask your insurer directly whether this split is available on your policy, since the option and the rules around it can vary.
Now that you know what deductible fits your situation, compare quotes to see what it would actually save you.
A parent revisits a deductible set years ago
A parent had a deductible set when their teenager first started driving, chosen low because new drivers get into more fender benders and the family wanted to avoid a big bill after a minor accident. Years later, the child was gone, driving their own car most of the year, and only borrowed the family car during visits home.
The parent requested quotes at a few deductible levels for the car that stayed home. Raising the deductible lowered the premium by an amount that, over time, was worth more than the extra risk, especially since the parent had enough in savings to cover the higher amount without any strain. They kept the second car's deductible lower since it was driven daily and used for a longer commute. The change left them with a policy that matched how the household actually used its cars, not how it used to.
Does raising my deductible lower my premium by a lot?
It depends on your driving history, your car, and your insurer, so there's no fixed amount to expect. The only way to know is to request quotes at different deductible levels and compare them directly. If the gap is small, it may not be worth the added risk. If it's meaningful and you can cover the higher amount in cash, it's usually worth taking.
Can I change my deductible without starting a new policy?
Yes, you can usually change your deductible at any point during your policy term, not just at renewal. Call your insurer or adjust it through your account, and ask when the change takes effect. Some insurers apply it immediately, others wait until your next billing cycle, so confirm the timing before you assume it's active.
What happens if my adult child causes an accident while visiting?
The deductible on whichever car they were driving applies, regardless of who's behind the wheel, as long as they're a permitted driver on your policy. If they drive occasionally and are already listed as an occasional driver, nothing changes. If they're not listed at all, check with your insurer before they drive, since an unlisted driver can complicate a claim.


