
What Happens if a Car Is Not Driven for a Year
A car that sits for a year still needs some form of coverage, or you risk a gap that costs you later.
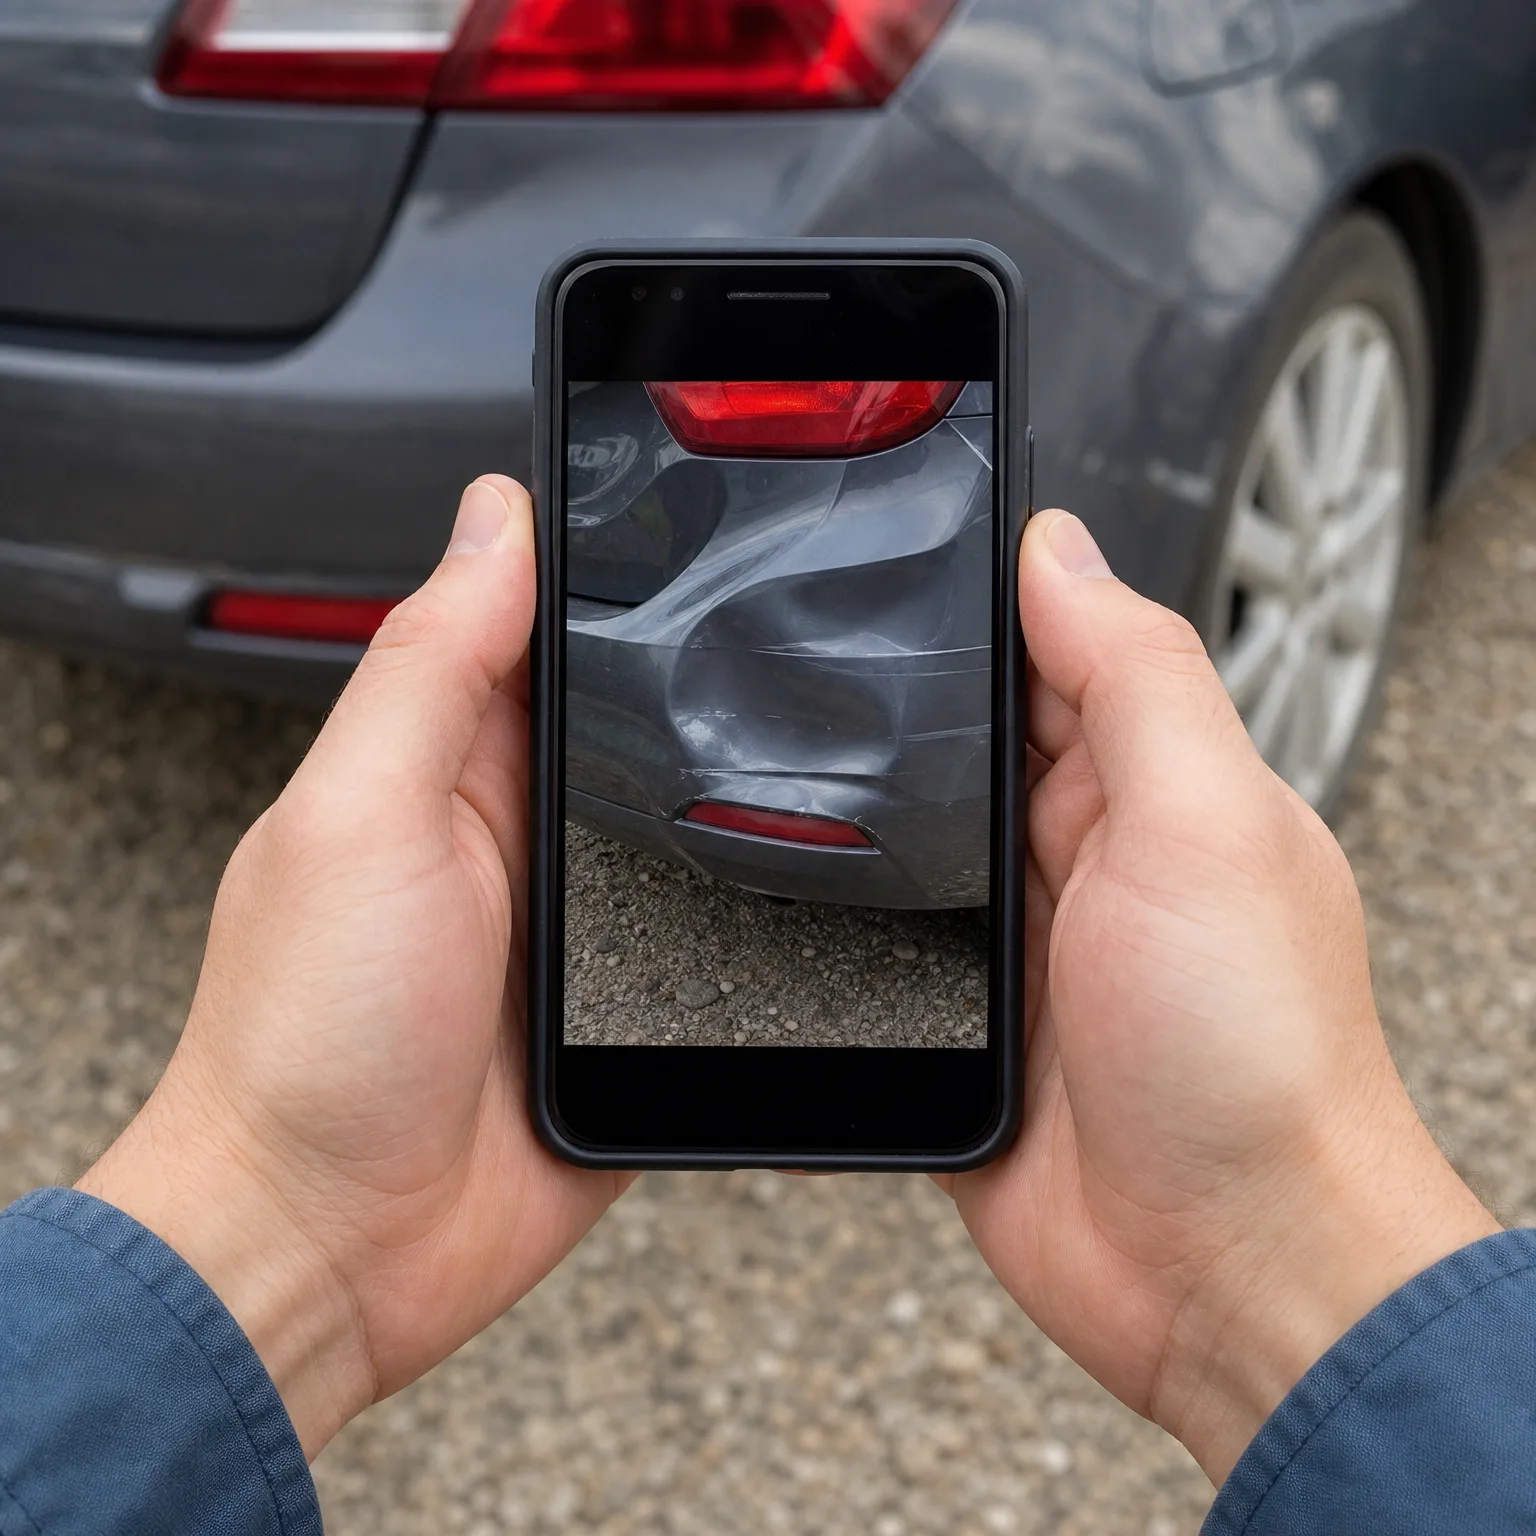
Here's what to decide before that unused car sits any longer
- Dropping coverage entirely If you cancel insurance completely, any damage, theft or liability while it sits uninsured is on you. Most states also require at least minimal coverage on a registered vehicle, so check what your state demands.
- Switching to storage coverage Comprehensive-only coverage protects against theft, fire or weather damage without paying for liability or collision you don't need while it's parked. Ask your insurer if this option exists and what it costs compared to full coverage.
- Keeping registration active An unused car can still need active registration if you want insurance without a lapse. Check your state's rules on non-operation status if you want to suspend both together.
- Avoiding accidental lapses A lapse shows up on your record even if the car never moved, and it can raise rates later when you do insure it again. Set a reminder or keep comprehensive coverage active instead of letting the policy quietly expire.
- Insuring an adult child's car If this is a car your grown child left behind, decide whether it stays on your policy or becomes theirs. A car sitting at your address with no listed primary driver is a question most insurers will ask eventually.
When the extra car in the driveway still had full coverage
A couple had a sedan that belonged to their son, who moved out two years earlier and only drove it when he visited twice a year. It still carried full coverage under their policy, the same as when he lived there and drove it daily. Neither of them had looked closely at the bill since he left.
They called their insurer and asked about switching the car to comprehensive-only coverage since it mostly sat parked. The insurer confirmed the car still needed to stay registered and insured at some level since it wasn't stored off the road permanently, but comprehensive-only was enough to protect against theft or weather damage without paying for liability or collision on a car nobody was really driving. When their son visited and drove it those few times a year, the policy still covered him since he was a listed occasional driver. The change lowered their premium right away, and they set a yearly reminder to review it again instead of letting it coast unnoticed for another two years.
The real decision isn't whether to keep coverage, it's whether you've looked at what it actually covers.
Once you know whether that car needs full coverage, storage coverage or none, compare quotes built around that choice.
Should you cancel coverage on a car that just sits there
If you do
If you cancel completely, you save the premium right away. But if anything happens to the car, theft, fire, a falling branch, you pay for it entirely yourself. In most states, a registered car still needs some coverage, so canceling without also handling registration can create a legal problem too.
If you don't
If you keep some coverage, usually comprehensive-only, you pay less than full coverage but you're protected against the most likely risks to a parked car. You avoid a lapse on your record, and when you're ready to insure it fully again, your history stays clean and your rate isn't penalized for a gap.
Does an unused car still need to stay registered?
In most places, yes, if you want it insured without creating a gap. Registration and insurance are usually linked, so letting one lapse while keeping the other active isn't straightforward and depends entirely on your state's rules.
Some states offer a non-operation or planned non-operation status that lets you suspend both registration and insurance together, which is the cleanest option if the car genuinely won't move for a long stretch. Other states don't offer this, which means your real choice is between full coverage, storage-only coverage, or dealing with the paperwork of deregistering and re-registering later. Check with your state's motor vehicle office directly, since this is one of the details that varies most and getting it wrong can mean fines or a registration lapse that follows the car.



