
When Should You Not File a Car Insurance Claim
Don't file when the damage costs less than your deductible plus the future rate hike you'd pay for filing.
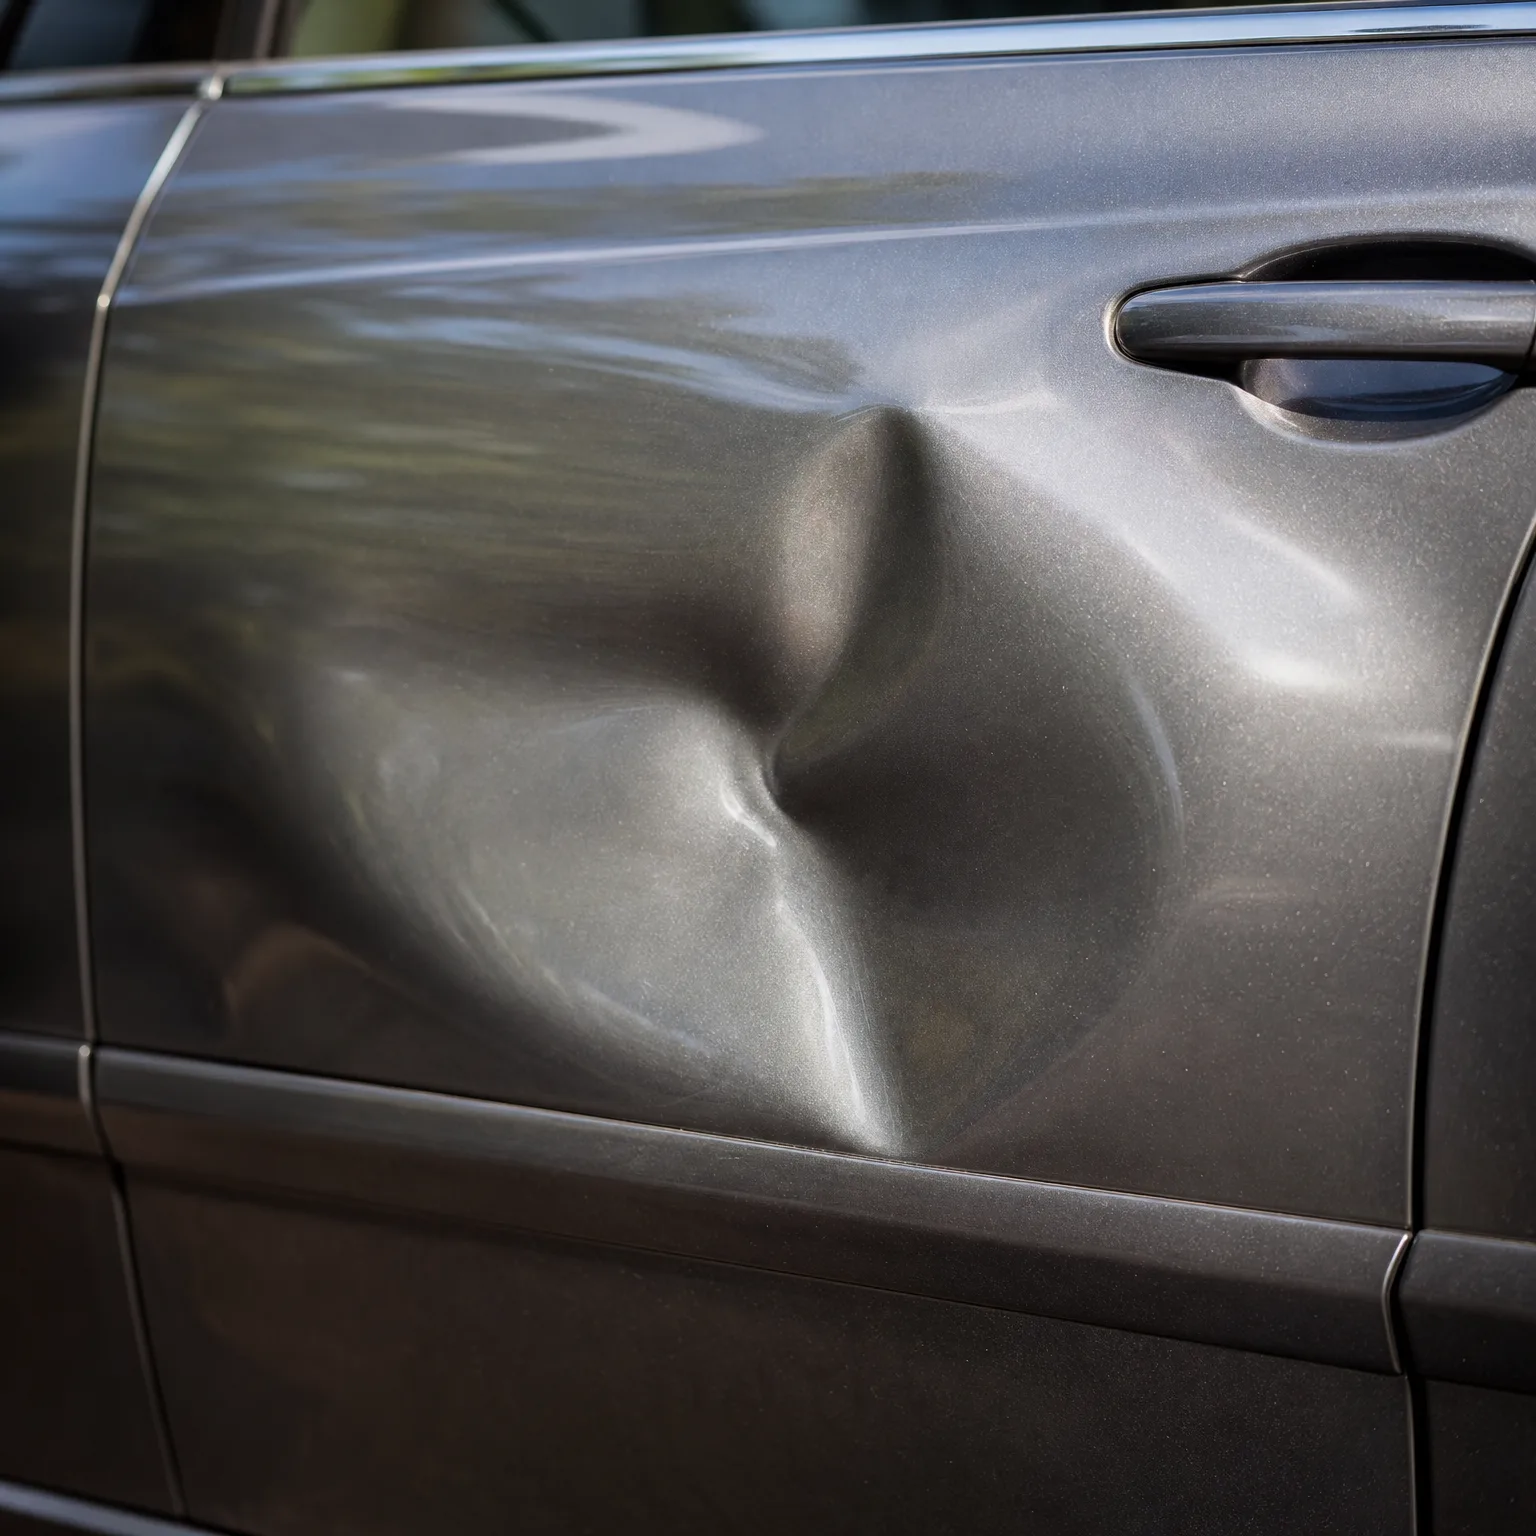
A parked-car dent in the driveway
One of your kids backed the extra car into the mailbox while home for a weekend. The bumper has a crack and a scrape, nothing structural, and a body shop quotes repair at an amount close to what your deductible already is. You're tempted to file because it feels like what insurance is for, but you stop to run the numbers first.
You call your agent and ask two things, what the deductible actually is on that car and whether a claim like this would raise the renewal rate. The agent confirms the repair cost barely clears the deductible, meaning you'd get very little back, and that an at-fault claim would stay on the record and affect pricing for years. You decide to pay for the bumper yourselves, keep the policy clean, and have a direct conversation with your kid about driveway speed instead.
Will not filing hurt me if I need to file later?
No, choosing not to file never hurts you. There's no penalty for staying quiet about damage you paid for yourself, and no insurer tracks near-misses or damage you never reported. Your record only reflects claims you actually filed, so skipping one keeps that record exactly as clean as it was before the damage happened.
What can hurt you is filing small claims repeatedly, because insurers do watch for patterns even if each individual claim seems minor. If you've already filed once or twice in recent years, that's a reason to lean toward paying out of pocket next time, since another claim on top of existing ones carries more weight than the same claim would on a clean record.

Now that you know which damage is worth filing, compare quotes to see what your claims history is costing you.
Deciding whether to call in a small claim
If you do
You report it, the insurer logs it as a claim even if they pay nothing, and it can appear in your claims history for years. Future rate quotes, with this insurer and others, may reflect it. If the payout is small, you can end up net negative once the rate change is factored in.
If you don't
You pay for repairs yourself and nothing goes on record anywhere. Your rate stays exactly where it is at renewal. The tradeoff is you cover the full cost now, so this only makes sense when that cost is close to or below what you'd keep after the deductible anyway.
Why small claims often cost more than they pay out
Insurance is priced on risk, and every claim you file becomes a data point insurers use to estimate your future risk, not just compensation for one incident. When you file for damage that barely exceeds your deductible, you're handing the insurer a reason to raise your rate while receiving very little money back. The math frequently works against you even though the claim feels justified in the moment.
The deductible is the first filter. Anything below it, you pay entirely yourself regardless of whether you file, so there's never a reason to report damage that costs less than your deductible. Anything only slightly above it is where the real decision lives, because the amount you'd actually receive after the deductible may be smaller than the rate increase spread over the next few years.
How much a claim raises your rate, and for how long, varies by insurer and by state, since some states limit how claims can be used in pricing or how long they can affect it. This is worth asking your agent directly, because the answer changes the math for your specific policy. A claim that's expensive in one state or with one insurer might be nearly weightless somewhere else.
The calculation changes when the damage involves another driver, a pedestrian, or significant structural harm to your own vehicle. In those cases the potential liability or repair cost usually dwarfs any rate concern, and filing is the right call regardless of deductible math. Small, self-contained, single-vehicle damage is where the question of whether to file is worth actually pausing on.
How many years does a claim stay on my record?
It depends on your insurer and your state, often somewhere in the range of several years, so ask your agent for the exact window on your policy. What matters more than the number is that the claim's effect on your rate usually fades gradually rather than dropping off all at once. A newer claim typically has a stronger effect than one from a few years back, and once enough time passes it stops influencing your rate at all. If you're close to that window passing, it may be worth waiting it out before filing anything new.
Does checking on a claim without filing it affect my rate?
No, simply calling to ask questions doesn't count as filing a claim and won't appear on your record. You can call your agent, describe the damage, ask what your deductible is, and ask how a claim like this would likely affect your rate, all without committing to anything. This is the right move whenever you're unsure, since it gives you real numbers instead of guesses. Only once you tell them to proceed does it become an actual claim that gets logged.
Should I remove my adult child from the policy or just lower their coverage?
It depends on whether they still drive your cars regularly, since removing someone who still drives occasionally can leave you without coverage if they're in an accident. If your adult child visits often and drives, keep them listed, possibly as an occasional driver if your insurer offers that option. If they've moved out permanently, have their own car and their own policy, and no longer drive yours, removing them is usually the right move and should lower your premium.


